 Asset Finance Broker of the Year
Finalist 2026
 Talk to James
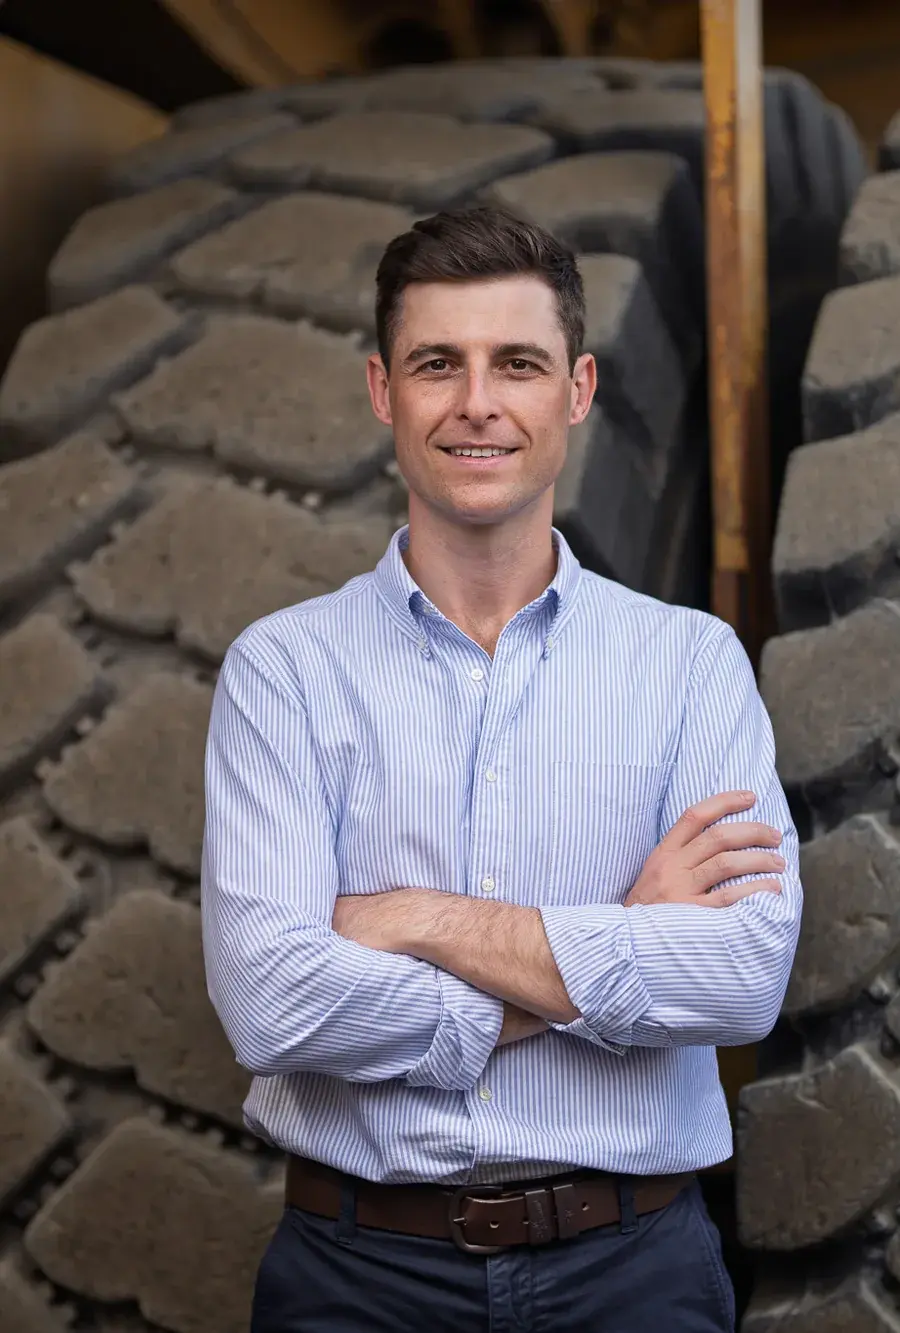
Every client works directly with James Allan, the director of MFG Finance. You deal business owner to business owner with someone who understands and relates to the pain points and pressure that come with growing a business.
Since entering the finance industry in 2013, James has worked across approximately $500 million in transactions. This experience gives his clients a significant advantage when procuring finance with someone who is highly experienced.
That experience extends from standalone transactions worth hundreds of thousands through to multi-million-dollar equipment purchases, revolving master facilities, major fleet refinances, business debt restructures and funding clients acquiring other businesses.
James operates beyond the standard transactional broker model of handling one deal at a time. He works as a long-term finance partner, giving clients visibility beyond the next machine and helping them understand the funding options available to support their broader growth strategy.
The MFG difference:
Asset Finance Broker of the Year CAFBA Emerging Broker
 Featured on the
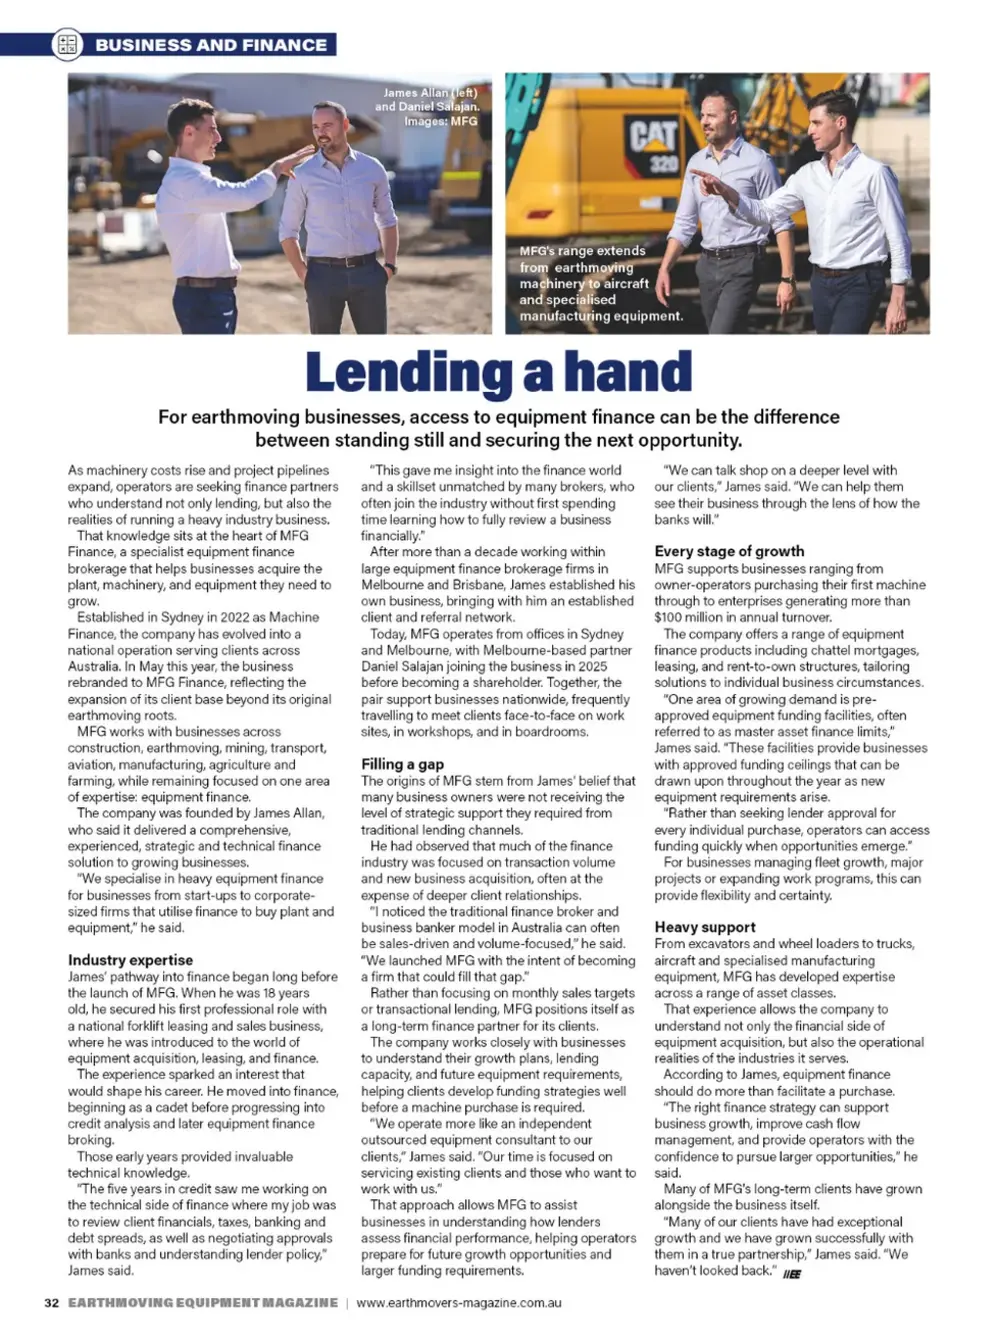 Featured article
The difference
Anyone can look at a single transaction in isolation. The harder job is understanding what approving that transaction today means for the next machine, the next project and the next stage of the business.
MFG starts by understanding where the business has been, where it is heading and what equipment is likely to be required along the way.
From there, we decide whether the right approach is to establish revolving limits with one or two major banks, spread transactions between several lenders, refinance existing debt, release equity from owned equipment or preserve particular lenders for future requirements.
The transaction matters. The position it leaves you in matters more.
A quick approval today means very little if it blocks the finance you need tomorrow.
Some of the loudest broker firms online are built around lead generation, sales teams and monthly settlement targets. The person responding to your enquiry may have limited equipment-finance experience, no direct relationship with the bank and no understanding of how today’s lender choice affects the next several transactions.
Heavy equipment finance is not one size fits all. A poorly presented application or lazy lender choice can burn valuable bank capacity, fragment debt across the wrong financiers and leave the business boxed in when the real growth opportunity arrives.
Getting the first deal approved is easy to celebrate. Living with where it was placed is the part that matters.
Valuable major-bank capacity can be consumed on a transaction that should have sat elsewhere, cutting off stronger options later.
A sloppy or poorly positioned submission can weaken lender confidence before the credit team has properly understood the business.
Your finance should not be placed according to a salesperson’s monthly target, preferred lender or the quickest path to settlement.
Fleet strategy
Every lender has different credit appetites, exposure limits and asset preferences. As a fleet grows, finance becomes less about rate, and more about the importance of choosing which lender should fund which transaction, and why.
Each approval changes the position of the pieces around it. The right lender spread protects major-bank capacity, keeps specialist options available and gives the business room to fund the next machine without having to undo decisions made six months earlier.
Map likely capex, replacement cycles and contract-driven equipment requirements before the purchase order lands. A clear view of the next 12 to 36 months lets us decide which lenders should be used now and which should be preserved.
Major-bank capacity is valuable. We avoid consuming it on transactions that can sit comfortably elsewhere, while making sure the business still has access to strong pricing and larger limits when the right opportunity arrives.
Debt should be spread with purpose, not scattered at random. We match the asset, transaction size, ownership structure and future fleet plan to the lender best positioned to support it.
Revolving and master limits create certainty around future acquisitions. When a machine becomes available or a contract requires immediate mobilisation, the funding pathway is already in place.
Client case studies
Getting the next machine funded is only one part of the job. MFG takes the time to understand the whole fleet, the debt behind it and where the business is heading, then stays involved as those requirements grow and change. These client relationships show what that support looks like in practice.
MMS · Western Australia
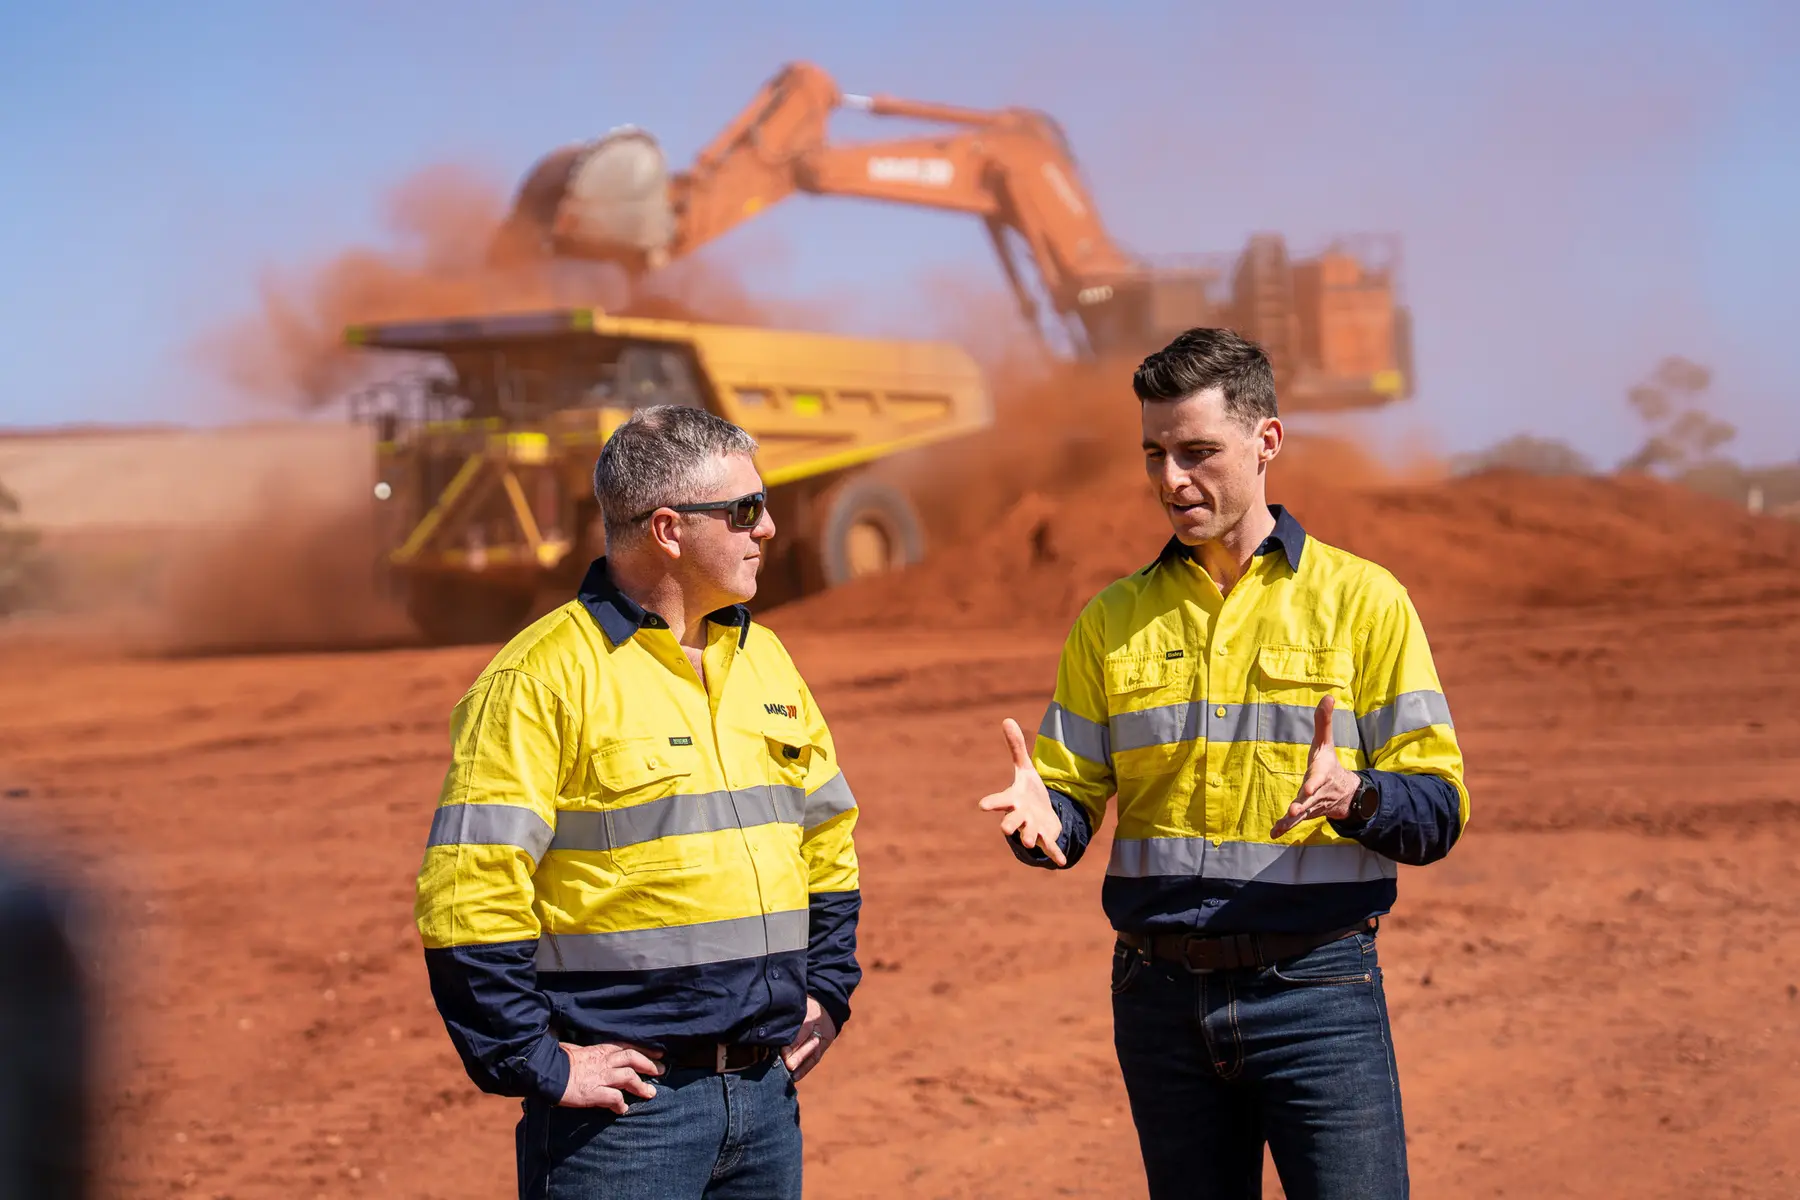
MFG was introduced to MMS in 2016, when the business turned over approximately $20 million. Today it turns over more than $250 million, with MFG supporting that growth across its mining-services contracting operation and gold mine projects.
We have funded more than 100 dump trucks, major 100–200 tonne Hitachi and CAT excavators, dozers, graders, water trucks, light vehicles and service trucks. We also introduced MMS to two major banks, including its house bank, and helped establish combined banking facilities exceeding $50 million.
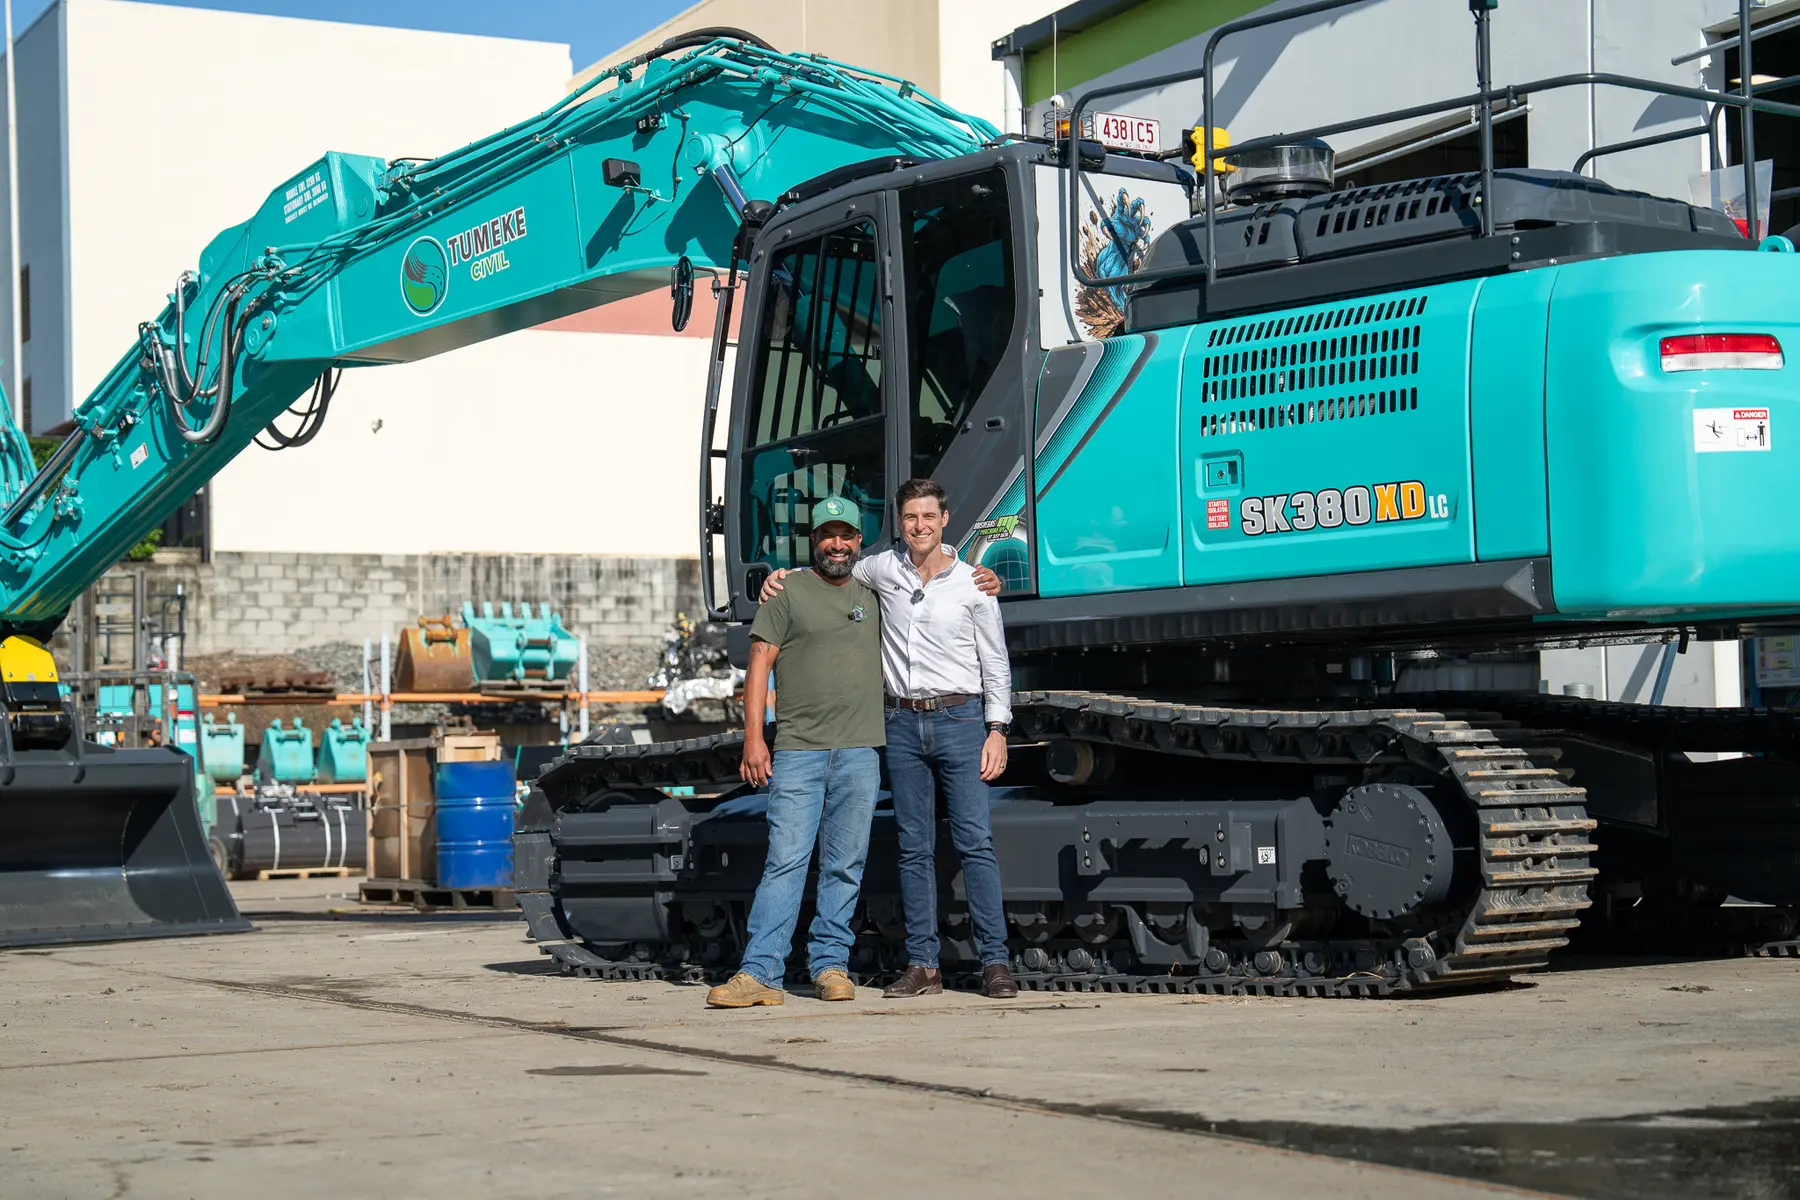
Tumeke Civil · Queensland
Introduced in 2025, MFG began by mapping every asset and its related loan balance so the owners could see exactly what the fleet owed and where equity sat.
Working closely with Marco at Brisvegas Machinery, six ageing excavators were replaced with new Kobelco machines ranging from 10 to 38 tonnes. Trade proceeds cleared the existing loans and available equity reduced the new borrowing. We also reset the finance strategy by removing balloons from the excavator fleet, helping the business build equity faster and make future replacements easier.
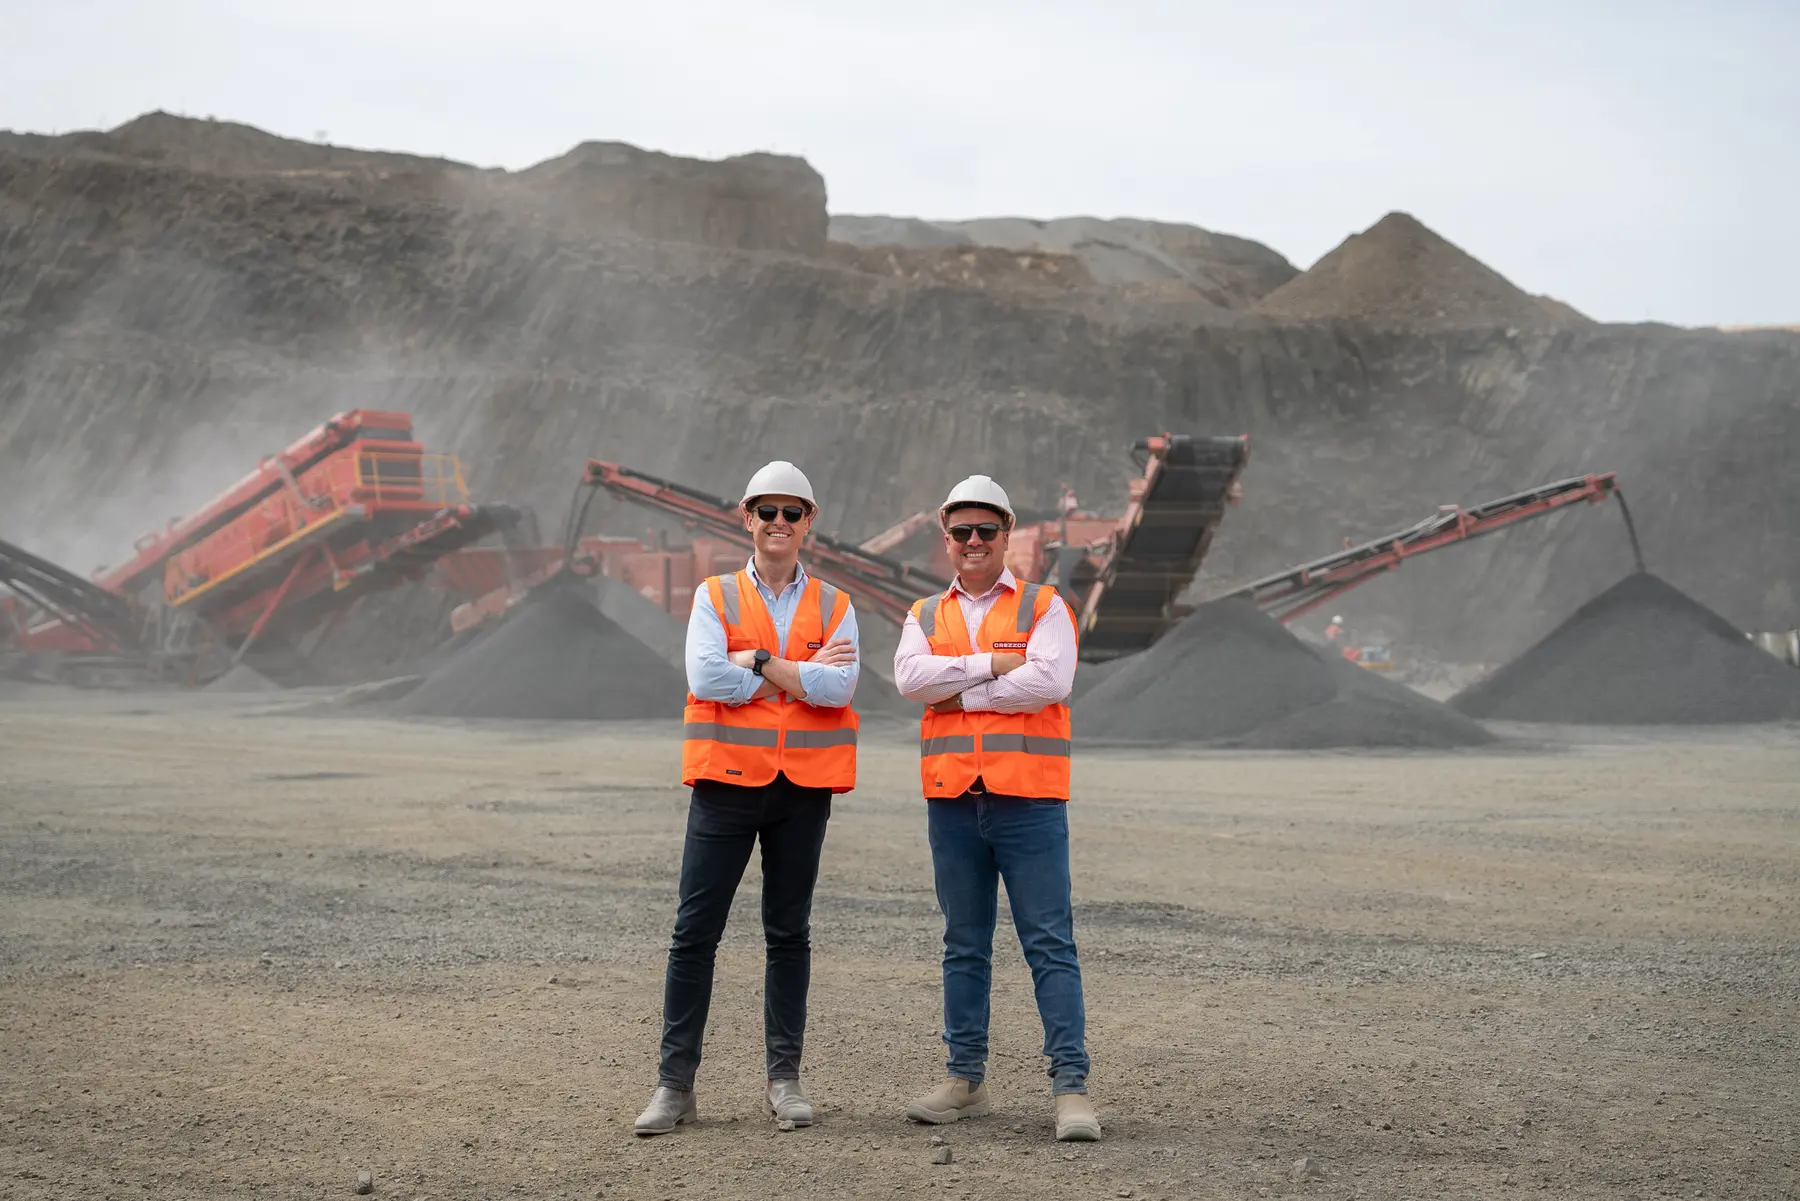
Crezzco · Tasmania
Crezzco approached MFG in 2024 while the company was being acquired by its current owner. We advised on the acquisition strategy, engaged a major bank and maintained the asset-finance support the business needed to keep operating and growing.
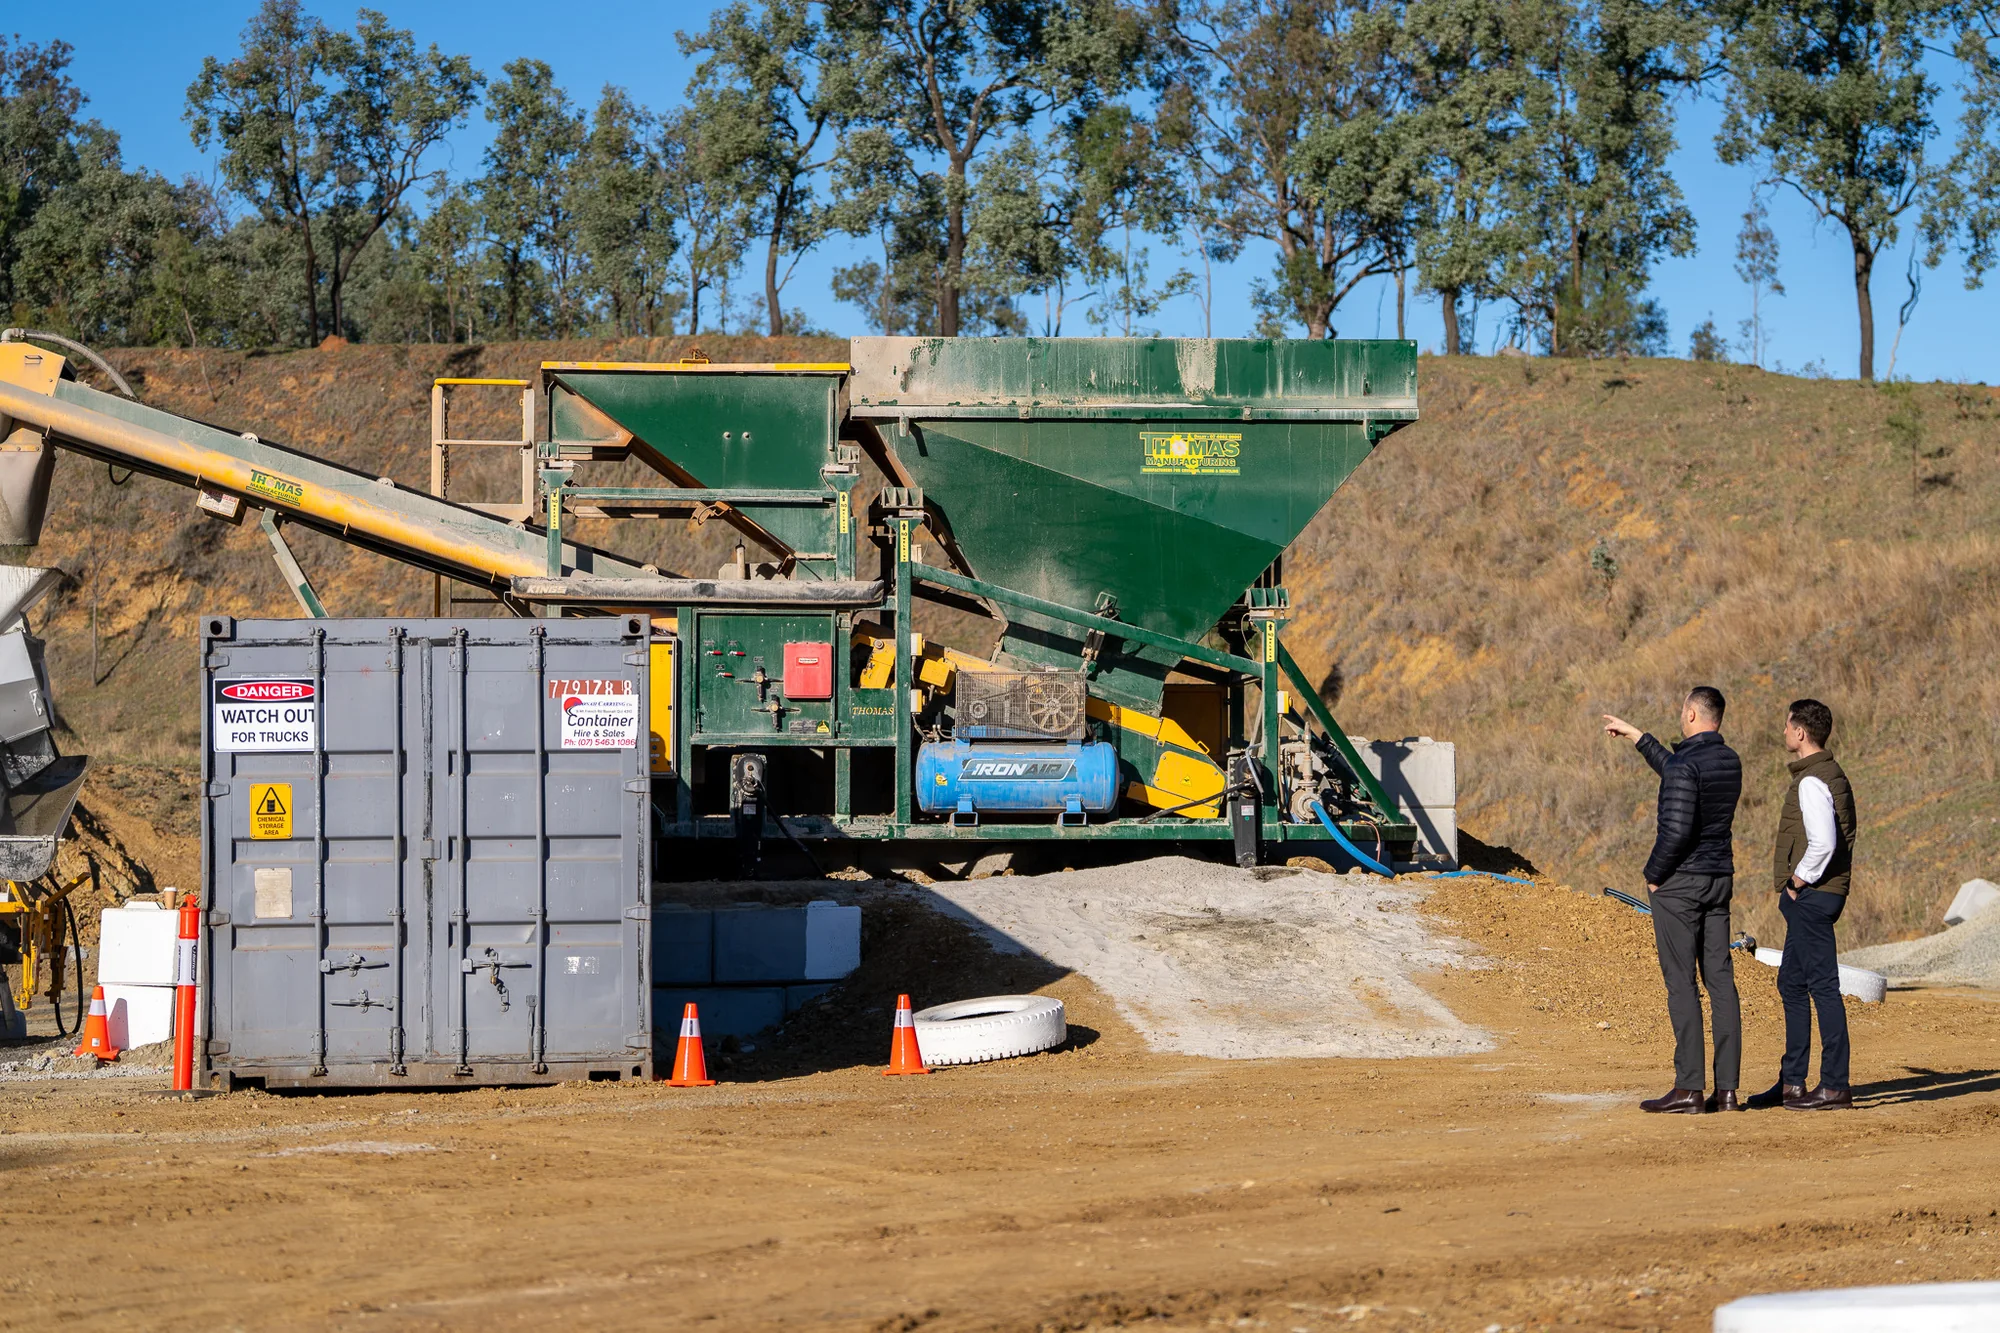
That included a multi-million-dollar purchase of Terex and Finlay crushing equipment sourced in regional Queensland and transported to Tasmania for a new quarry contract. We have also supported the replacement of an ageing haulage fleet with new Kenworth tippers and trailers, together with loaders, excavators, rollers, forklifts, service trucks and light vehicles.
KBH Earthmoving · Queensland
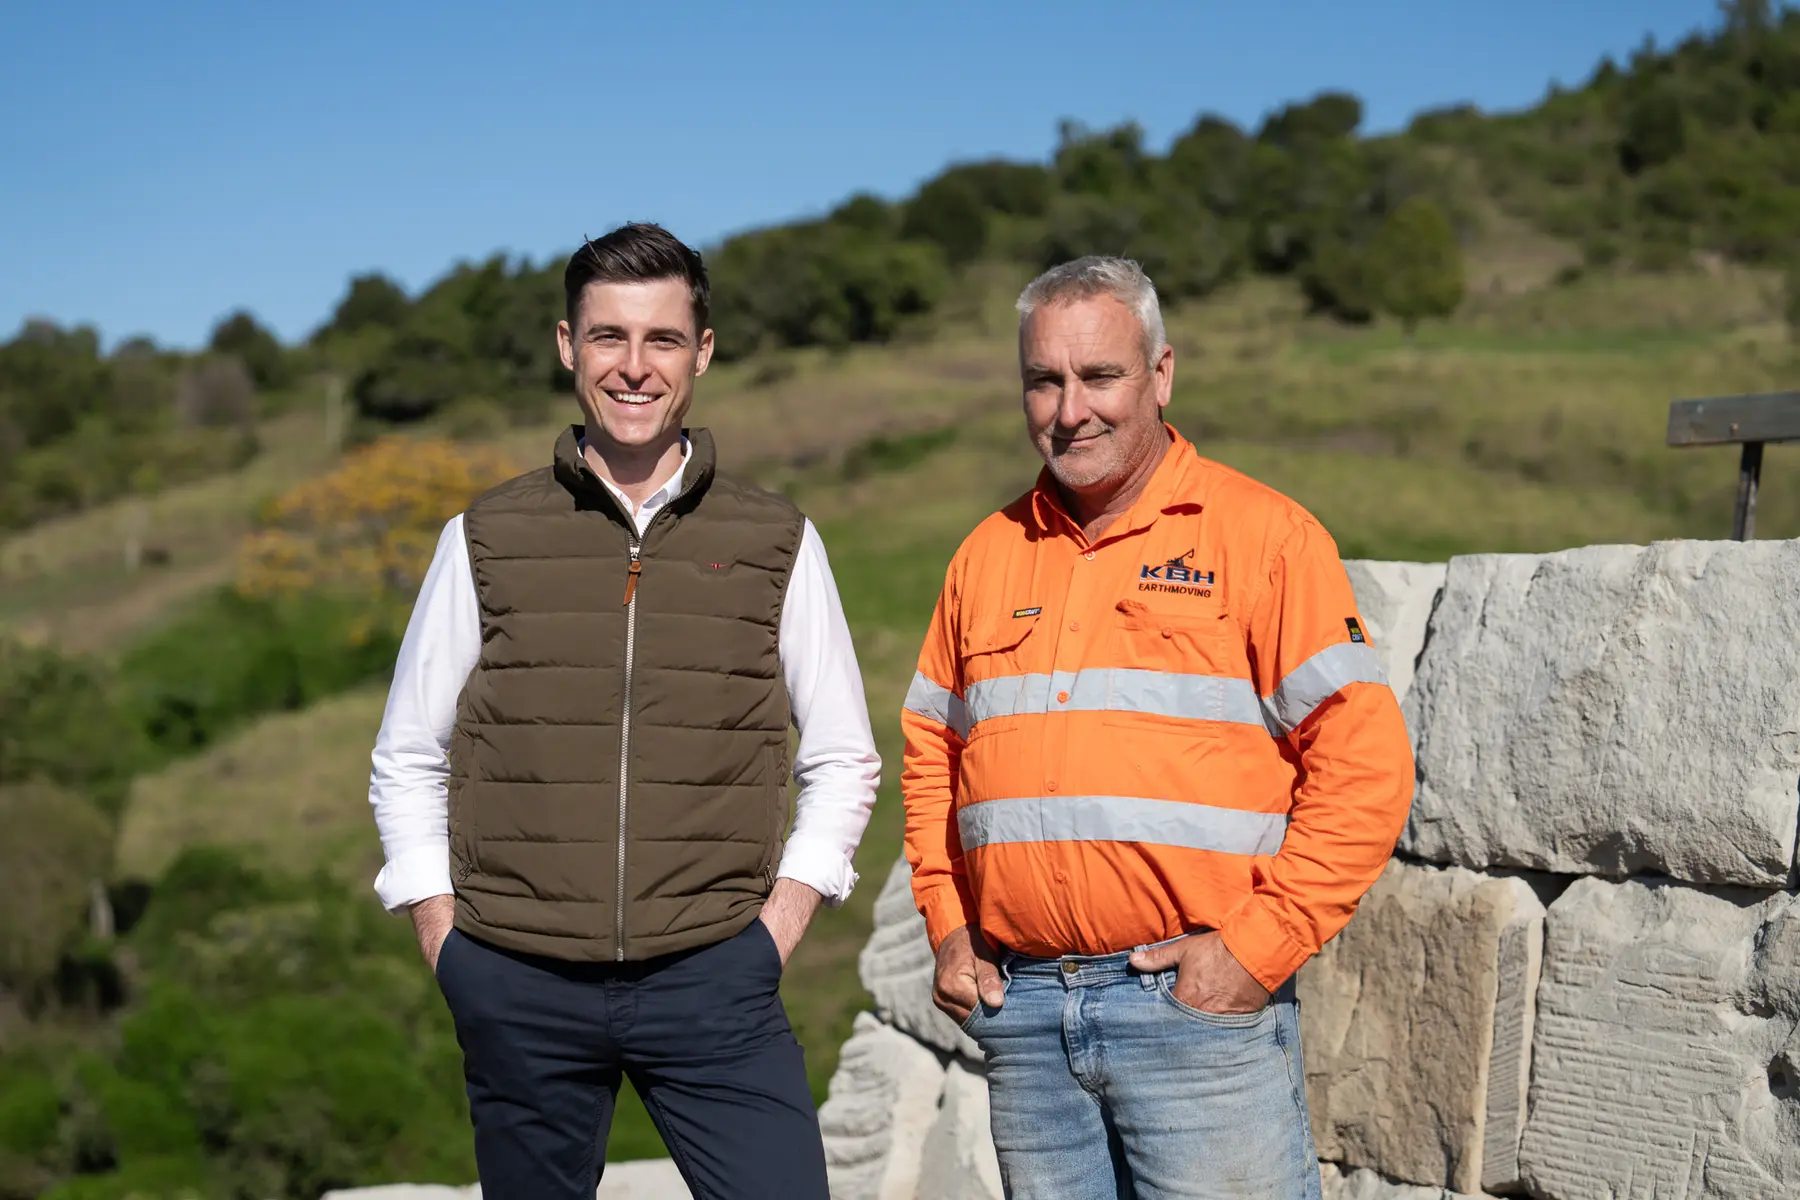
MFG took over the relationship in 2022 when KBH needed a finance partner who understood fleet funding and the importance of acting quickly when equipment became available.
Since then, we have facilitated more than 66 purchases across the business: CAT and Hitachi excavators from 15 to 40 tonnes, CAT and John Deere graders, Kenworth and Mack tippers, water carts, skid steers, a prime mover and low-loader combination, GPS systems, tilt rotators, grapples and a mobile concrete batching plant.
HRV Earthmoving · Victoria
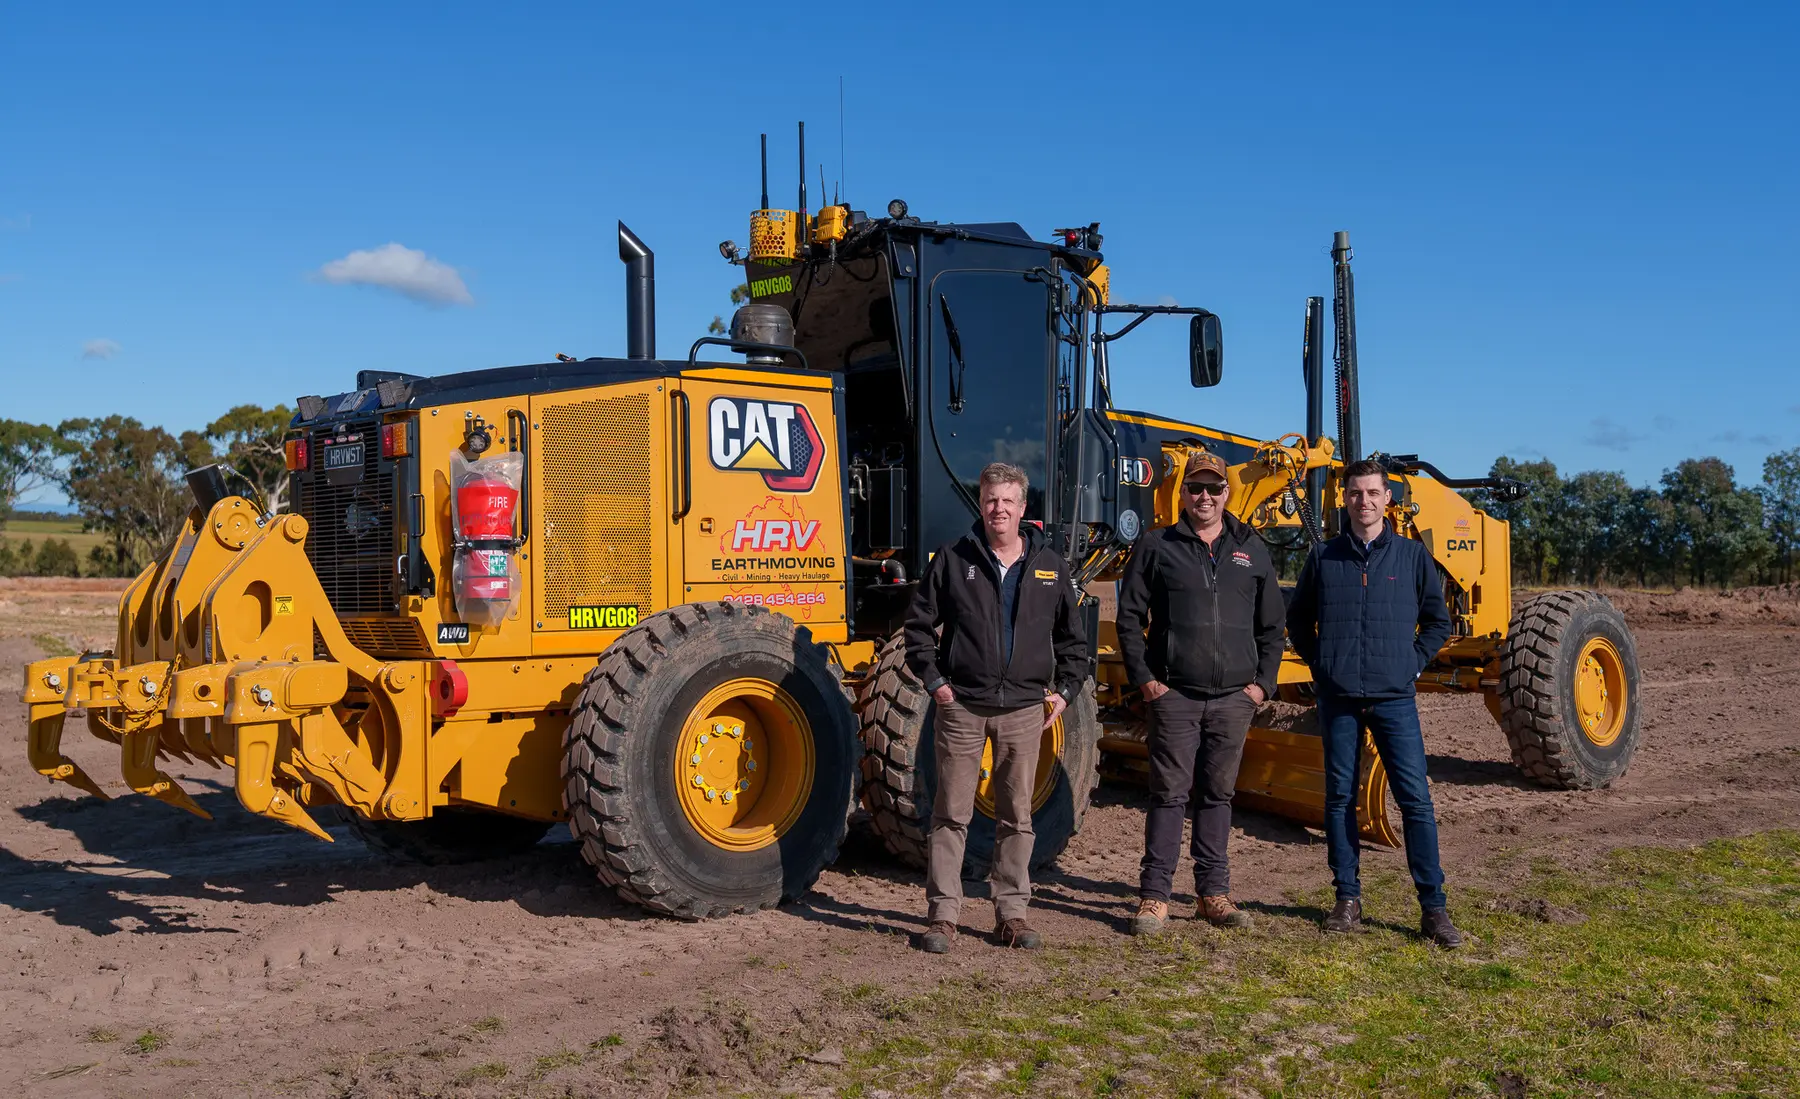
Introduced in 2024, MFG mapped HRV’s fleet and debt strategy from day one. We helped sell ageing CAT graders and dozers, replace them with newer equipment and move the business into major-bank relationships for more competitive pricing.
Non-bank capacity remains available when speed matters, while a pragmatic spread across major banks preserves room for future purchases. Working with the owner and accountant, we keep financial information ready so the business can move quickly on graders, dozers, trucks, trailers, light vehicles and GPS attachments.
One relationship
By dealing with MFG and working with James, you have a partner for life. You should not have to repeatedly explain your business to a new banker or broker, or awkwardly rebuild a relationship every time someone changes banks, moves roles or leaves the industry.
MFG becomes the consistent relationship that knows what you do, how the fleet is funded and where the business is heading. We identify the right banks, facilities and people for each stage, make the introductions and stay involved when the personnel at the bank inevitably change.
You maintain one long-term relationship with someone who understands the whole picture, while still gaining access to the wider lending market and the right banking specialists when they are needed.
What we solve
Map payouts, trade timing and new approvals so ageing assets can be cycled out without disrupting operations.
Build a funding plan around plant required for a new contract, including staged acquisitions and lender capacity.
Move quickly on the immediate machine without weakening the wider lender strategy.
Establish pre-approved capacity for repeat acquisitions through the year.
Refinance equipment debt, release equity or rebalance exposure where the current structure no longer suits the business.
Dealer, auction, private-sale, import and progress-payment transactions where the process needs more management.
RPO structures with either a fixed buyout position or a rebate-style outcome similar to arrangements offered by some OEMs.
When equipment needs to move out of the fleet, we can connect you with trusted specialists who sell machinery on consignment.
Release equity from unencumbered or lowly geared equipment to create liquidity while retaining use of the assets.
In the field
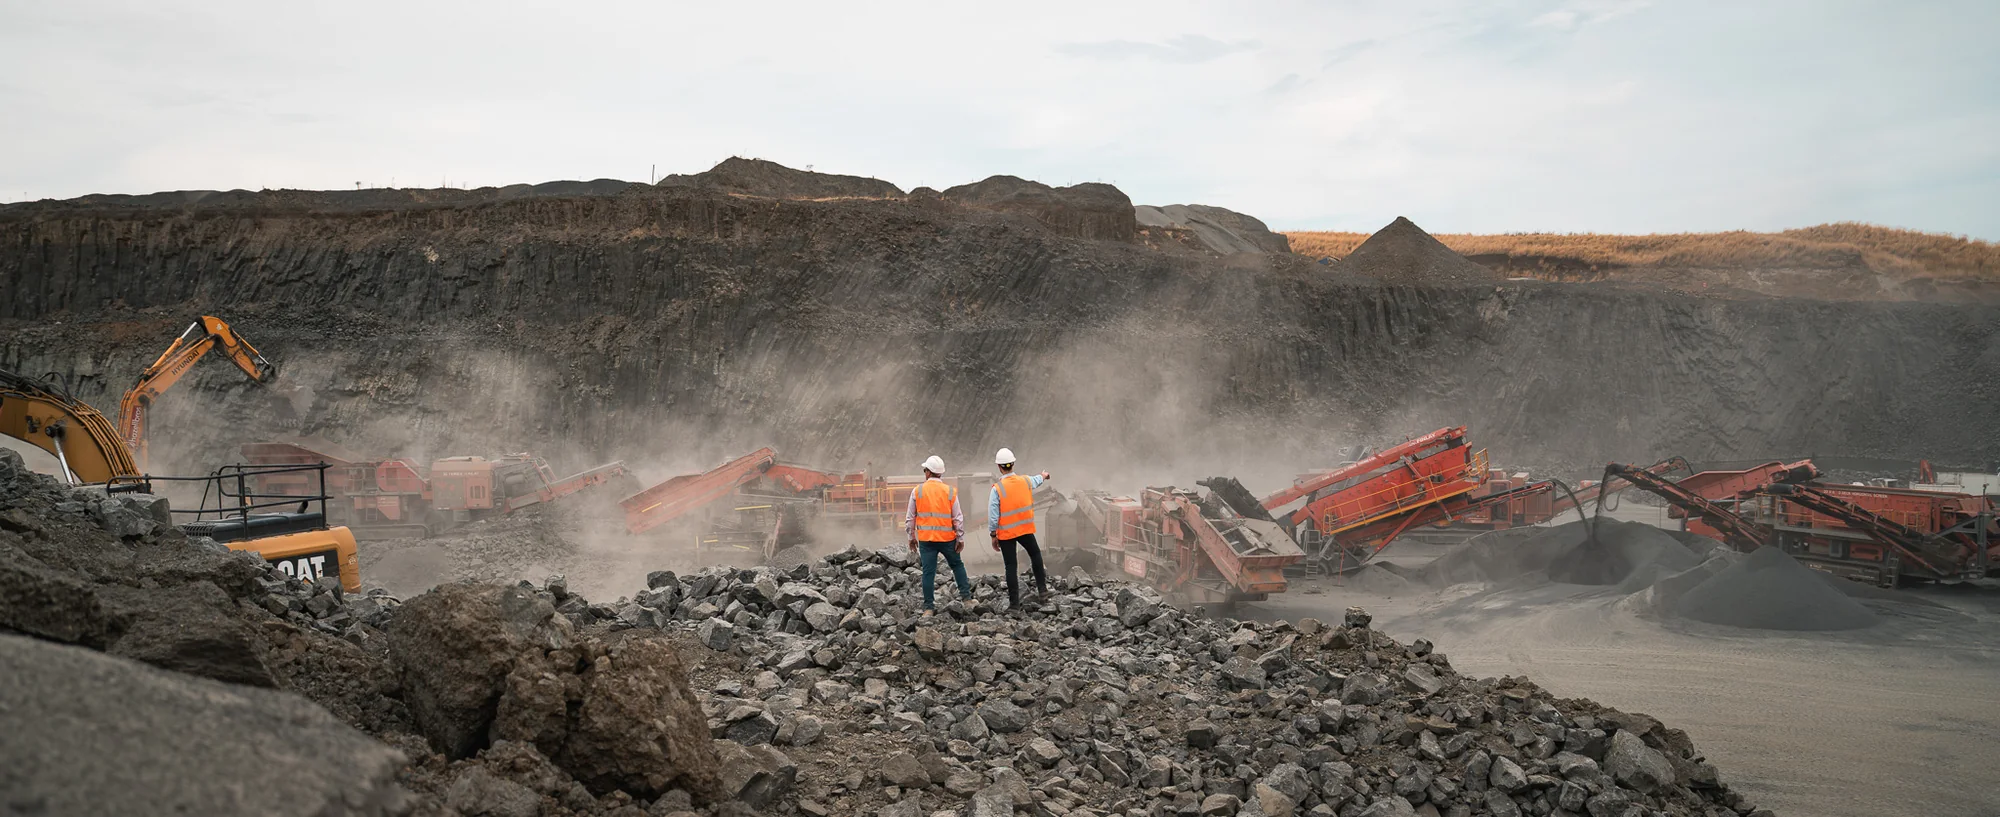
From civil yards in Victoria to active mine sites in Western Australia, our advice is grounded in the equipment, the contracts and the people behind the operation.
Accredited and accountable
MFG is directly accredited with all major banks, alongside an extensive panel of non-bank, specialist and private lenders.
Those accreditations are maintained through consistent submission quality, strong compliance, ethical conduct and proven performance. MFG has never lost a lender accreditation.
 CAFBA 101556
 FBAA M-359967
 AFCA 89354
Because our bank accreditations are direct, we never need another broker firm to lodge an application on our behalf. Your information stays with MFG and the lender handling the transaction, protecting your privacy while keeping the process fully compliant from a data-protection and insurance perspective.
Panel shown is indicative and subject to lender accreditation, credit policy and transaction requirements.
Our approach
History, financial performance, entities, current debt, contracts and where the business is going.
Current equipment, payouts, replacement cycles and the next 12–36 months of likely capex.
Decide where facilities should sit, which lenders to preserve and where revolving limits make sense.
Execute each acquisition while keeping the broader funding position moving in the right direction.
Talk to James
Whether you are replacing one machine, mobilising for a contract or planning a major fleet program, give us the wider picture. Every enquiry comes directly to James.
Commercial and business-use enquiries only. Australia-wide.